Startup Equity Dilution Explained: How Founder Ownership Changes During Fundraising
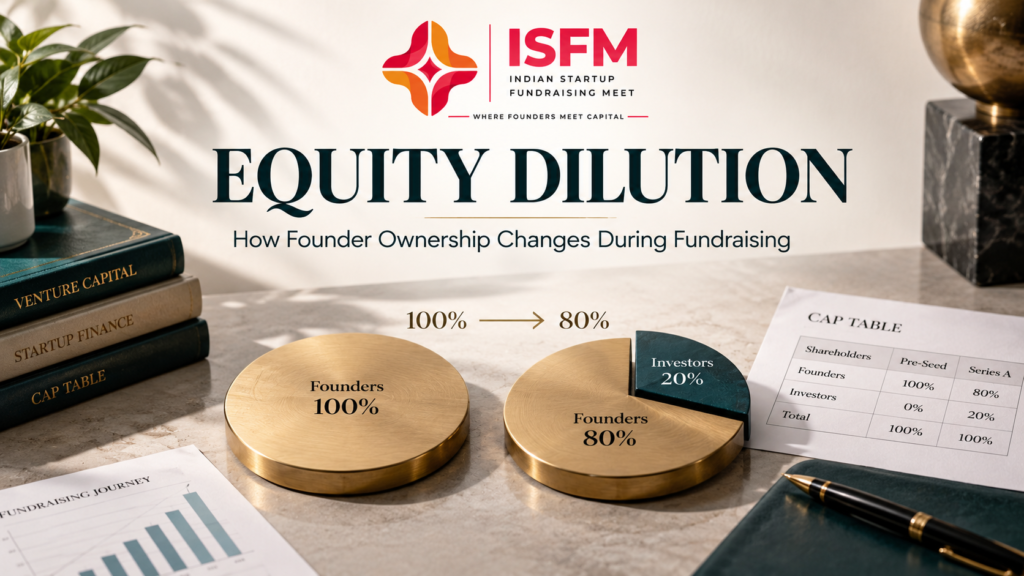
Equity dilution is one of the most important concepts startup founders must understand before raising investment. When a company issues new shares to investors, the percentage ownership of existing shareholders generally decreases. However, dilution is not automatically a disadvantage. Its impact depends on the valuation, investment terms, amount of capital raised and the business value created through that financing.
Imagine you own 100% of a startup.
An investor offers ₹1 crore to help you expand the business.
In exchange, the investor wants a 20% ownership stake.
After the investment, you may own 80% rather than 100%.
Does that mean you have lost value?
Not necessarily.
If the investment helps your company achieve meaningful growth, a smaller ownership percentage could eventually represent greater economic value than your original larger percentage.
However, poorly planned dilution can create significant problems.
Founders may give away too much equity too early, misunderstand the effect of multiple funding rounds, ignore employee stock option pools or agree to investment terms without calculating their long-term consequences.
For Indian startups preparing to approach angel investors, venture capital firms or strategic investors, understanding equity dilution is an essential part of fundraising readiness.
In this comprehensive guide, ISFM – Indian Startup Fundraising Meet explains what startup equity dilution means, how to calculate it, how pre-money and post-money valuations work, how ownership changes across multiple funding rounds and how founders can make more informed fundraising decisions.
What Is Equity Dilution in a Startup?
Equity dilution is the reduction in an existing shareholder’s percentage ownership when additional shares or other equity interests are issued or become effective under the relevant financing structure.
To understand dilution, consider a simple startup with 10,000 issued shares.
A founder owns all 10,000 shares.
The founder’s ownership is therefore 100%.
The company then issues 2,500 new shares to an investor.
The total issued shares become 12,500.
The founder still owns 10,000 shares, but the ownership percentage changes.
Founder Ownership = 10,000 ÷ 12,500 × 100 = 80%
Investor Ownership = 2,500 ÷ 12,500 × 100 = 20%
The founder has not necessarily sold any personal shares.
Instead, the company has issued new shares, increasing the total number of outstanding shares.
This is commonly called primary equity dilution.
Why Does Equity Dilution Happen?
Dilution can occur through several transactions.
1. New Equity Investment
A startup may issue shares to angel investors, venture capital funds or other eligible investors in exchange for capital.
2. Employee Stock Option Pools
Companies may reserve or issue equity interests for employees under applicable incentive arrangements.
The creation or expansion of an option pool can affect fully diluted ownership.
3. Convertible Instruments
Certain financing arrangements may convert into equity in the future.
Their conversion can change the company’s ownership structure.
4. Future Funding Rounds
A startup may issue additional shares during seed, Series A, Series B or later investment rounds.
5. Other Equity-Linked Transactions
Warrants, additional share issuances and other arrangements may affect shareholding according to their actual terms.
Not every transaction has the same dilution impact.
For example, when an investor purchases existing shares directly from a founder, the founder transfers ownership to the buyer, but the company does not necessarily issue new shares.
The total number of shares may remain unchanged.
This is different from a primary investment that increases the company’s issued share capital.
Understanding Pre-Money and Post-Money Valuation
Two important concepts in startup fundraising are pre-money valuation and post-money valuation.
What Is Pre-Money Valuation?
Pre-money valuation is the agreed valuation of a company immediately before receiving the new primary equity investment.
What Is Post-Money Valuation?
Post-money valuation is the implied value immediately after including the new primary investment.
For a straightforward priced equity round:
Post-Money Valuation = Pre-Money Valuation + New Investment
Example
Suppose a startup is valued at ₹4 crore before investment.
An investor agrees to invest ₹1 crore.
| Item | Amount |
|---|---|
| Pre-money valuation | ₹4 crore |
| New primary investment | ₹1 crore |
| Post-money valuation | ₹5 crore |
| New investor ownership | 20% |
| Existing shareholders’ combined ownership | 80% |
The new investor’s ownership is calculated using:
Investor Ownership = Investment ÷ Post-Money Valuation × 100
Therefore:
₹1 crore ÷ ₹5 crore × 100 = 20%
These calculations assume a simple priced round without additional option-pool changes, convertible instruments or other negotiated adjustments.
The Most Common Dilution Calculation Mistake
Founders sometimes calculate investor ownership by dividing the investment amount by the pre-money valuation.
For example:
₹1 crore ÷ ₹4 crore = 25%
They may conclude that the investor will own 25%.
But the correct calculation for this straightforward primary investment is:
₹1 crore ÷ ₹5 crore = 20%
The distinction matters.
Investor ownership in a straightforward priced primary round is generally calculated using the post-money valuation, not the pre-money valuation.
How to Calculate Equity Dilution Step by Step
Founders can use the following process for a simple priced equity investment.
Step 1: Determine the Pre-Money Valuation
Suppose the company’s agreed pre-money valuation is ₹8 crore.
Step 2: Identify the Investment Amount
The investor proposes investing ₹2 crore.
Step 3: Calculate the Post-Money Valuation
₹8 crore + ₹2 crore = ₹10 crore.
Step 4: Calculate New Investor Ownership
₹2 crore ÷ ₹10 crore × 100 = 20%.
Step 5: Calculate Existing Shareholders’ Remaining Ownership
100% − 20% = 80%.
Step 6: Apply the Dilution to Existing Shareholders
Suppose the ownership structure before the round was:
| Shareholder | Before investment |
|---|---|
| Founder A | 60% |
| Founder B | 40% |
| Total | 100% |
After the new investor receives 20%, the existing shareholders retain a combined 80%.
Each existing shareholding is multiplied by 80%.
| Shareholder | Before investment | After investment |
|---|---|---|
| Founder A | 60% | 48% |
| Founder B | 40% | 32% |
| New investor | 0% | 20% |
| Total | 100% | 100% |
This is a simplified example assuming both founders are diluted proportionately.
In actual investment transactions, additional rights or securities can affect the final calculation.
What Is Founder Dilution?
Founder dilution refers to the reduction in the founders’ ownership percentages.
For example, two founders may initially own 100% of a company collectively.
After a seed investment, they may own 80%.
Following another round, their combined ownership may fall further.
This does not mean their number of shares must decrease.
Their relative share of the company becomes smaller because the total equity base increases.
Why Founder Dilution Matters
Ownership can influence:
- Economic participation in future business value.
- Voting rights.
- Governance arrangements.
- The ability to raise future capital.
- Founder incentives.
- Employee equity allocation.
- Potential proceeds from future liquidity events.
However, ownership percentage alone does not fully determine governance control or economic outcomes.
Different share classes and contractual rights may affect voting powers, liquidation distributions and decision-making.
How Dilution Works Across Multiple Funding Rounds
Founders frequently underestimate the cumulative effect of repeated equity financing.
Consider a fictional startup where the founders initially own 100%.
Seed Round
The company issues 20% ownership to a seed investor.
The founders retain 80%.
Series A
The company then completes another financing in which the new investor acquires 20% of the post-round equity.
The existing shareholders are diluted proportionately by another 20%.
| Shareholder | After Seed | After Series A |
|---|---|---|
| Founders | 80% | 64% |
| Seed investor | 20% | 16% |
| Series A investor | 0% | 20% |
| Total | 100% | 100% |
The founders’ ownership falls from 80% to 64%.
The seed investor’s percentage also declines from 20% to 16%.
Series B
Assume a further 20% primary equity financing.
| Shareholder | After Series A | After Series B |
|---|---|---|
| Founders | 64% | 51.2% |
| Seed investor | 16% | 12.8% |
| Series A investor | 20% | 16% |
| Series B investor | 0% | 20% |
| Total | 100% | 100% |
After three rounds, the founders collectively hold 51.2%.
The amount of capital raised and valuation may have increased substantially, but the founders’ percentage has decreased.
This example excludes employee option pools, convertible securities and other financing adjustments.
Dilution compounds across funding rounds. It should be modelled before accepting each new investment.
Does Dilution Mean Founders Are Losing Money?
Not necessarily.
A percentage reduction is not the same as an actual economic loss.
Consider the following hypothetical example.
Before Investment
A founder owns 100% of a startup valued at ₹2 crore.
The implied value of the founder’s ownership is ₹2 crore.
After Investment
An investor contributes ₹1 crore at a ₹4 crore pre-money valuation.
The post-money valuation is ₹5 crore.
The investor receives 20%.
The founder retains 80%.
At the transaction’s implied post-money valuation, the founder’s stake is worth:
80% × ₹5 crore = ₹4 crore.
The founder’s ownership percentage has declined, but the implied value of the remaining stake is higher than before.
However, this does not mean the founder has received ₹4 crore in cash or that the stake can be sold at that price.
Startup valuations are negotiated transaction values, not guaranteed realisable proceeds.
Future company performance, investor rights, liquidity conditions and transaction terms affect the actual economic outcome.
Why Some Dilution Can Be Beneficial
Equity investment may allow a startup to access resources that would otherwise be unavailable.
The financing might support:
- Product development.
- Commercial expansion.
- Research and testing.
- Customer acquisition.
- Recruitment.
- Manufacturing capacity.
- Working capital.
- Strategic expertise and industry relationships.
If these resources help the business create meaningful value, dilution may be commercially justified.
A founder retaining 70% of a successful company may be better positioned economically than one owning 100% of a company unable to progress.
But positive outcomes are not guaranteed.
The benefits of dilution depend on the company’s ability to use capital effectively.
What Is an Employee Stock Option Pool?
An Employee Stock Option Plan (ESOP) is an arrangement through which eligible employees may receive rights to acquire shares under specified terms.
A startup may also establish an option pool to reserve equity for future employee grants.
This can help attract and retain skilled personnel.
However, the option pool affects ownership calculations.
Example
Suppose two founders initially own 100% of the company.
The company establishes a fully diluted employee option pool representing 10% of the post-pool equity.
The founders’ combined fully diluted ownership becomes 90%.
The option pool accounts for the remaining 10%.
This simplified calculation assumes an appropriately structured pool and no other securities.
Why ESOP Pools Matter During Fundraising
Investors may require an employee option pool to be created or expanded as part of a financing transaction.
The timing of that expansion can significantly affect founder dilution.
Pre-Money ESOP Pool vs Post-Money ESOP Pool
One important financing negotiation concerns whether the employee option pool is created or expanded before or after the investment.
Pre-Money Option Pool
An option pool created or expanded as part of the pre-money capitalisation generally places more of the dilution burden on existing shareholders.
The new investor’s negotiated post-round percentage may remain protected.
Post-Money Option Pool
An option pool created after the financing may dilute the new investor along with existing shareholders, depending on the transaction structure.
Why Founders Should Pay Attention
Two funding offers with the same headline pre-money valuation and investment amount may produce different founder ownership outcomes when option-pool terms differ.
The correct approach is to request a complete pro forma fully diluted cap table showing the ownership structure after all financing adjustments.
What Is a Fully Diluted Cap Table?
A capitalisation table, commonly called a cap table, records ownership and equity-related interests in the company.
A fully diluted cap table models ownership after accounting for the relevant shares, options and equity-linked instruments under the specified assumptions.
Depending on the company, the cap table may include:
- Founder shares.
- Existing investor shares.
- Employee options.
- Unallocated option pools.
- Convertible instruments.
- Warrants.
- Other contractual equity rights.
Founders should not rely exclusively on the current issued-share percentage when evaluating a proposed financing.
A fully diluted model can reveal future ownership effects that are not immediately visible in the current share register.
How Convertible Instruments Affect Dilution
Some startups raise early capital through instruments that may convert into equity at a later stage.
Examples include convertible notes and certain other equity-linked financing arrangements.
In some international startup markets, SAFEs are also used.
What Is a SAFE?
A Simple Agreement for Future Equity (SAFE) is a contractual instrument commonly associated with Y Combinator’s startup financing framework.
A SAFE generally provides for equity to be issued under specified future events.
Its conversion mechanics depend on the particular agreement, valuation cap, discount and other provisions.
What Is a Valuation Cap?
A valuation cap generally affects the valuation used to determine the conversion economics of an eligible instrument.
What Is a Discount?
A conversion discount may allow an investor to receive equity at a lower price than investors participating in a subsequent priced financing round.
Why These Instruments Require Care
Multiple convertible instruments may cause more dilution than founders initially expect.
Founders should model all outstanding instruments before negotiating a new investment.
Important for Indian startups: US-style SAFE documentation should not be assumed to be automatically suitable or legally interchangeable with financing instruments available under Indian law. Indian companies should obtain professional advice on permissible instruments, issuance requirements, valuation and applicable foreign-investment rules.
Equity Dilution vs Equity Transfer
These concepts are different.
Primary Share Issuance
The company issues new shares.
The total number of shares increases.
Existing shareholders’ percentage ownership generally decreases.
The investment proceeds ordinarily go to the company.
Secondary Share Transfer
An existing shareholder sells or transfers shares to another party.
The total issued share count generally does not change.
The selling shareholder’s ownership decreases and the buyer’s ownership increases.
The company may not receive the transaction proceeds.
A financing round can sometimes combine primary and secondary components.
Founders should clearly distinguish how much capital is entering the business from how much is being paid to existing shareholders.
Dilution vs Valuation: What Should Founders Prioritise?
A high valuation may appear attractive because it can reduce the percentage of ownership issued for a given investment amount.
But valuation is only one part of the financing decision.
Investors may negotiate other important rights.
These can include:
- Liquidation preferences.
- Board representation.
- Protective provisions.
- Reserved matters.
- Anti-dilution provisions.
- Information rights.
- Founder vesting.
- Transfer restrictions.
- Pro-rata participation rights.
A transaction with a higher headline valuation may be less attractive when other rights and obligations are considered.
Founders should assess the complete financing package rather than focusing solely on the percentage being sold.
What Is Anti-Dilution Protection?
Anti-dilution protection is a term used in certain investment agreements to describe mechanisms that may adjust an investor’s economic position following specified future financing events.
For example, some preferred equity investments contain provisions that operate when a later financing occurs at a lower share price.
These provisions can be structured in different ways.
Broad-Based Weighted-Average Protection
Certain agreements adjust conversion pricing based on a formula that considers relevant shares and financing terms.
Full-Ratchet Protection
Under specified contractual structures, the adjustment may reference the lower price of a subsequent financing round.
The impact can be materially different.
Founders should review the exact formula and transaction documents with qualified advisers.
Anti-dilution protection does not mean an investor’s percentage ownership can never decrease. Its effect depends on the contractual provisions and triggering events.
What Are Pro-Rata Rights?
Pro-rata rights may allow an existing investor to participate in future financing rounds to help maintain its percentage ownership.
The actual rights depend on the agreement.
For example, an investor owning 10% may have an opportunity to purchase additional shares in a later round so that its percentage remains closer to 10%.
However, exercising these rights generally requires additional investment.
Pro-rata participation can affect the allocation available to new investors and other shareholders.
Founders should understand these rights before agreeing to them.
How Much Equity Should a Founder Give to Investors?
There is no universally correct dilution percentage.
The appropriate amount depends on:
- Startup valuation.
- Capital requirement.
- Development stage.
- Market conditions.
- Business risk.
- Expected milestones.
- Future financing needs.
- Existing ownership.
- Employee equity requirements.
- Negotiated investment terms.
A founder should not decide that giving 10%, 15% or 20% equity is automatically appropriate without examining the underlying transaction.
Instead, calculate the financing requirement and model ownership consequences.
Compare Different Fundraising Scenarios
Suppose a company has a ₹5 crore pre-money valuation.
| Investment amount | Post-money valuation | New investor ownership |
|---|---|---|
| ₹50 lakh | ₹5.5 crore | 9.09% |
| ₹1 crore | ₹6 crore | 16.67% |
| ₹1.5 crore | ₹6.5 crore | 23.08% |
| ₹2 crore | ₹7 crore | 28.57% |
These figures assume a simple primary priced equity round with no additional adjustments.
The comparison illustrates why the amount raised matters as well as the valuation.
Raising more money is not automatically beneficial if the company cannot productively use it.
How to Reduce Unnecessary Founder Dilution
Founders cannot always avoid dilution when financing growth through new equity.
However, they can take steps to avoid unnecessary ownership loss.
1. Raise Capital Against Specific Milestones
A well-defined financing requirement can help prevent raising significantly more equity capital than the business needs.
2. Build Stronger Business Evidence
Product validation, commercial traction and financial discipline may improve the startup’s position in investment discussions.
They do not guarantee a particular valuation.
3. Compare Capital Instruments
Consider whether equity, suitable debt, grants or internal funding matches the intended business activity.
4. Model Future Rounds
Prepare ownership scenarios for the current round and likely future financings.
5. Negotiate the Option Pool Carefully
Understand whether an option pool increase occurs before or after the investment.
6. Maintain an Accurate Cap Table
Include all relevant equity-linked rights and outstanding instruments.
7. Avoid Unnecessary Early Equity Commitments
Consider the long-term consequences of equity granted to advisers, partners and other stakeholders.
8. Understand the Entire Term Sheet
Review liquidation rights, governance provisions, preferences and future financing obligations.
9. Consider Capital Efficiency
Improving the relationship between expenditure and business progress may reduce the total external financing required.
10. Seek Professional Transaction Advice
A qualified legal and financial review can help identify dilution effects that are difficult to understand from headline terms alone.
Common Equity Dilution Mistakes
Mistake 1: Confusing Pre-Money and Post-Money Valuation
Incorrect calculations can result in misunderstanding the ownership being sold.
Mistake 2: Focusing Only on the Investment Amount
The amount raised does not explain dilution without considering valuation and transaction structure.
Mistake 3: Ignoring Employee Option Pools
A pre-money pool expansion may create more founder dilution than expected.
Mistake 4: Failing to Model Future Rounds
Ownership reductions can compound across multiple financings.
Mistake 5: Overlooking Convertible Instruments
Future conversions may change the effective ownership structure.
Mistake 6: Assuming Higher Valuation Always Means Better Terms
Governance and economic rights also matter.
Mistake 7: Using an Outdated Cap Table
An inaccurate ownership model can complicate investor due diligence.
Mistake 8: Confusing Secondary Sales With Primary Fundraising
A secondary transfer may not provide operating capital to the startup.
Mistake 9: Granting Excessive Equity Without Planning
Unnecessary equity commitments can create difficulties during future funding rounds.
Mistake 10: Ignoring Legal and Regulatory Requirements
Indian startups must consider applicable corporate and securities requirements and, where relevant, foreign-investment regulations.
Equity Dilution for Indian Startups
Indian founders should pay particular attention to the legal structure of their equity financing.
Depending on the transaction, relevant matters may include:
- Authorised and issued share capital.
- Articles of Association.
- Shareholder approvals.
- Board resolutions.
- Share valuation.
- Share allotment.
- Statutory company filings.
- Shareholder agreements.
- Employee stock option arrangements.
- Applicable tax consequences.
- Foreign direct investment requirements.
- Applicable foreign exchange reporting and pricing rules.
The treatment of convertible instruments and equity-linked securities depends on their legal structure and applicable law.
The company should not assume that every financing method used in the US startup ecosystem can be directly replicated in India.
Professional corporate, legal, tax and financial guidance may be necessary.
How to Explain Dilution to Co-Founders
Before accepting an investment offer, the founding team should understand the proposed transaction.
A clear internal discussion should address:
- How much capital is being raised?
- What is the pre-money valuation?
- What is the post-money valuation?
- How much ownership will the new investor receive?
- What will each founder own after the round?
- Will an ESOP pool be created or expanded?
- Are convertible instruments outstanding?
- What rights will the investor receive?
- How might future rounds affect ownership?
- Does the proposed financing support a credible business milestone?
All founders should review the same pro forma cap table and transaction assumptions.
Practical Equity Dilution Checklist
| Readiness area | Question to verify |
|---|---|
| Funding requirement | Is the amount justified? |
| Pre-money valuation | Is the agreed figure clear? |
| Post-money valuation | Has it been calculated correctly? |
| Investor stake | Is the expected percentage confirmed? |
| Founder ownership | Is each founder’s post-round percentage modelled? |
| Cap table | Is the current ownership record accurate? |
| Fully diluted equity | Are relevant options and instruments included? |
| ESOP pool | Is the pool size and timing understood? |
| Convertible instruments | Are future conversion effects modelled? |
| Investor rights | Have economic and governance terms been reviewed? |
| Future rounds | Have reasonable dilution scenarios been prepared? |
| Legal documentation | Are applicable requirements identified? |
| Capital utilisation | Are funding milestones clearly defined? |
Completing this checklist does not establish that the financing terms are optimal.
It helps founders identify questions that should be resolved before signing.
How ISFM Supports Startup Valuation and Dilution Awareness
ISFM – Indian Startup Fundraising Meet is a private startup fundraising facilitation initiative focused on structured startup evaluation and relevant connections within the entrepreneurship and investment ecosystem.
For equity-seeking startups, valuation and ownership considerations are important aspects of fundraising readiness.
Founders should understand the proposed investment amount, the likely ownership impact and the financing requirements associated with their development stage.
ISFM’s preliminary founder screening is a basic readiness and eligibility review and should not be confused with independent expert evaluation.
Following applicable nomination and screening requirements, independent domain experts may evaluate the startup in greater detail.
Relevant evaluation areas may include:
- Business model and target market.
- Development stage.
- Founder and management capability.
- Product readiness.
- Commercial traction.
- Financial planning.
- Capital requirement.
- Funding utilisation.
- Proposed valuation assumptions.
- Cap table and ownership clarity.
- Investor readiness.
The objective is to encourage better-informed funding preparation and relevant ecosystem engagement.
ISFM does not determine a guaranteed market valuation or guarantee investor meetings, investment selection, financing approval or fund disbursement.
Investment valuations and transaction terms remain subject to negotiation, due diligence, applicable legal requirements and independent investor decisions.
Frequently Asked Questions About Startup Equity Dilution
1. What is equity dilution?
Equity dilution is the reduction in existing shareholders’ percentage ownership when new shares or other equity interests increase the relevant ownership base.
2. Does raising equity funding dilute founder ownership?
In a typical primary equity issuance, yes. The percentage depends on the valuation, investment amount and additional financing terms.
3. How is equity dilution calculated?
For a simple priced round, calculate post-money valuation and divide the new primary investment by that amount to estimate new investor ownership.
4. What is the difference between pre-money and post-money valuation?
Pre-money is the agreed value before new investment. Post-money includes the new primary investment.
5. If an investor puts ₹1 crore into a startup valued at ₹4 crore pre-money, what percentage do they receive?
Under a simple priced primary round, the post-money valuation is ₹5 crore and the investor receives 20%.
6. Does dilution mean founders lose money?
Not automatically. Ownership percentage may fall while the implied value of the remaining stake rises, but future economic outcomes are uncertain.
7. Can dilution happen multiple times?
Yes. Additional equity issuances across future funding rounds can further reduce existing ownership percentages.
8. What is ESOP dilution?
It is the ownership impact associated with creating, expanding or issuing employee equity interests under the relevant capital structure.
9. What is a fully diluted cap table?
It is an ownership model incorporating the relevant shares, options and equity-linked instruments under specified assumptions.
10. What is pre-money ESOP dilution?
It refers to the dilution effect when an option pool is incorporated into the pre-money capital structure before new investment.
11. Can grants dilute founder equity?
Grants that do not require equity generally do not cause ownership dilution by themselves. However, funding terms must be reviewed carefully.
12. Does debt funding cause dilution?
Ordinary debt generally does not involve issuing equity. Certain debt instruments may include conversion or equity-linked features.
13. What are pro-rata rights?
They may give investors contractual rights to participate in future financing to maintain their ownership percentage.
14. What is anti-dilution protection?
It refers to contractual mechanisms that may adjust specified investor economics in certain financing circumstances.
15. Can a founder avoid all dilution?
A founder may avoid equity dilution by not issuing new equity, but doing so may limit certain financing options.
16. Is giving 20% equity to investors too much?
It depends on the company’s valuation, funding requirement, development stage and negotiated terms. No single percentage is appropriate for every startup.
17. Can a founder retain control after dilution?
Potentially, but governance depends on voting rights, share classes, shareholder agreements and other legal arrangements—not ownership percentage alone.
18. Does a high valuation always reduce dilution?
For a fixed amount of straightforward primary equity investment, a higher pre-money valuation generally implies a lower percentage sold. Other transaction terms can change the overall effect.
19. Should founders calculate dilution before signing a term sheet?
Yes. They should review the proposed ownership structure, option pool and relevant future financing assumptions.
20. Does ISFM guarantee a particular startup valuation or funding outcome?
No. ISFM facilitates startup evaluation and ecosystem engagement, while valuation and investment decisions remain with the relevant parties.
Conclusion: Understand Dilution Before Raising Capital
Equity dilution is a normal part of many startup fundraising journeys.
As companies raise capital, issue employee options and complete additional funding rounds, their ownership structures can change.
These changes are not automatically harmful.
The important question is whether the financing helps create sufficient business value to justify the equity and contractual rights being granted.
Founders should understand pre-money valuation, post-money valuation, investor ownership, option pools, convertible instruments and future fundraising scenarios before accepting an investment proposal.
A properly maintained cap table and clear financial model can help make these decisions more transparent.
The objective is not simply to retain the highest possible ownership percentage. It is to build a valuable, sustainable company while making informed decisions about capital and control.
Before signing an equity investment agreement, founders should know exactly how the financing affects their ownership today and how future rounds may change it.
Raise Capital With Clarity. Understand Your Equity. Build Long-Term Value.
ISFM – Indian Startup Fundraising Meet
Where Founders Meet Capital
Official Website: https://www.indianstartupfundraisingmeet.com
Startup Nomination: https://zfrmz.in/A1pyKmrRj1s9OIsgPR4I
Investor & Partner Collaboration: https://zfrmz.in/p5cGk97nqrKp2ZXaJqjl
WhatsApp Community: https://chat.whatsapp.com/BNFh80tJsCtJEvgCQsW2i4
Official WhatsApp Channel: https://whatsapp.com/channel/0029VbDbOmr2ZjCkYLBeIw1T
Contact: +91 7014264283
Disclaimer: This article is for general educational purposes and does not constitute legal, tax, accounting, valuation or investment advice. Actual dilution depends on share capital, instrument terms, option pools, transaction agreements and applicable law. ISFM does not guarantee valuation, investor selection or funding approval.